
Corning (GLW) Q3 Earnings Preview: Can AI Optical Momentum Continue and Springboard Acceleration Be Validated?
 2026/10/26 06:08
1. Investment Highlights Overview
Corning (GLW.US) is scheduled to report third-quarter 2026 results before the market open on October 27, 2026. Wall Street consensus expects revenue of approximately $5.0 billion (+17% to +22% YoY) and core EPS of about $0.88 (+31% YoY). The company’s own guidance is for core sales of $4.9–5.0 billion (~+16% YoY) and core EPS of $0.85–0.89 (~+28% YoY). Consensus has moved toward the high end of guidance, with the whisper number near $0.89. The key focus is whether strong AI-driven optical growth can be sustained, whether Enterprise Networks and Gen AI shipments continue to convert, and whether the Springboard plan (targeting a $20 billion annualized sales run rate by the end of 2026) remains on track or is accelerating. After a sharp pullback from June highs, the market is highly sensitive to growth quality and valuation.
Focus 1: Sustainability of Optical Communications and Enterprise Networks Growth
Optical Communications is the primary growth engine. In Q2, the segment generated $2.07 billion in sales (+32% YoY), with net income up 77% and a record margin of 21%. Enterprise Networks grew 65%, while Gen AI-related revenue nearly doubled. Investors will watch whether Q3 Enterprise growth remains elevated, whether AI data-center orders are translating into actual shipments, and the progress of long-term agreements with hyperscalers such as Amazon, NVIDIA, and Meta. Any slowdown could raise questions about the durability of the AI optical cycle.
Focus 2: Springboard Plan Progress and Annualized Run-Rate Validation
Corning previously raised its Springboard targets, aiming for a $20 billion annualized sales run rate by the end of 2026, $30 billion by 2028, and $40 billion by 2030, while entering a phase of accelerating growth. Management has hinted that the $20 billion milestone could be reached one quarter early. The report will be scrutinized for whether Q3 results approach or exceed the high end of guidance and for any commentary on the run-rate trajectory and the new Photonics platform, both of which are central to the long-term narrative.
Focus 3: Margin Expansion and Improvement in Other Businesses
In Q2, core operating margin expanded to 20.9%, gross margin reached 39.6%, and free cash flow was strong. For Q3, the market will monitor whether Optical margins can hold or improve further, whether the Solar business returns to profitability after a maintenance shutdown, and whether Carrier recovers (it grew only 1% last quarter). At the same time, Specialty Materials faces pressure from higher memory prices, which management expects to reduce handheld unit volumes by a mid-teens percentage this year.
Focus 4: Valuation Digestion and Re-rating Potential After Sharp Pullback
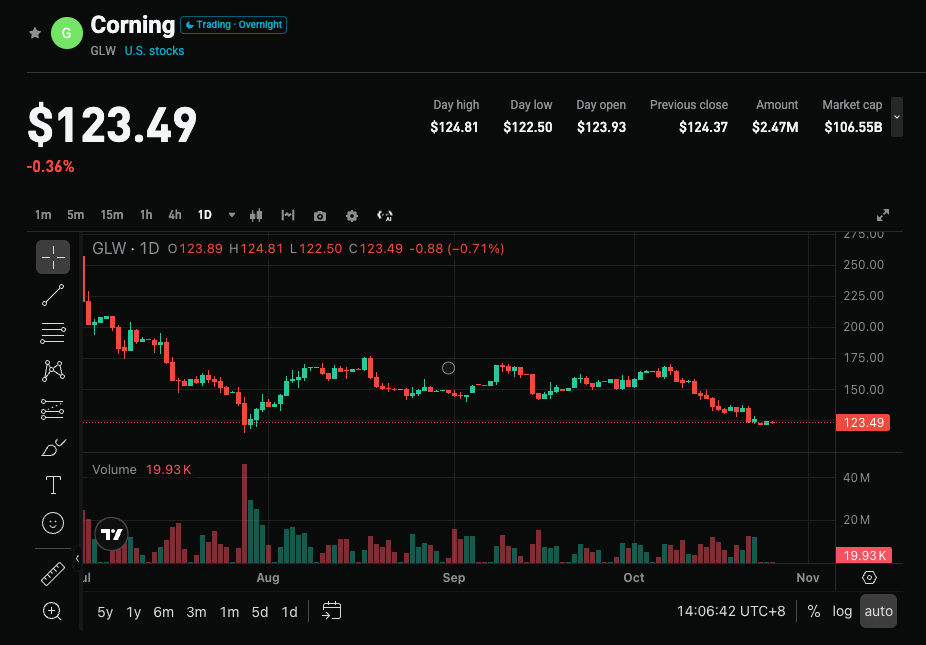
Shares have fallen sharply from their June peak of around $270 to the $120–130 range, bringing valuations down but still leaving the stock sensitive to growth quality. Sentiment has shifted from slightly cautious to modestly constructive, yet the stock has frequently sold off on earnings days even after beats. Management’s tone on the second-half outlook and longer-term targets will be a key sentiment inflection point.
3. Risks and Opportunities
Upside Catalysts:
- Optical and Enterprise growth remains strong (Enterprise near or above 60%), with clear acceleration in AI shipments.
- Revenue and EPS reach or exceed the high end of guidance, and management confirms the Springboard $20 billion run rate is on track or ahead of schedule.
- Optical margins hold at record levels, Solar returns to profitability, and free cash flow stays robust.
Downside Risks:
- Results merely meet the midpoint of guidance or come in light, with Enterprise growth decelerating and raising concerns that the AI optical cycle is peaking.
- Persistent weakness in Carrier, continued drag from Specialty Materials due to soft handset demand, or higher capex pressuring free cash flow.
- Cautious forward commentary from management, combined with residual valuation pressure, triggering further downside.
4. Trading Strategy Considerations
Bullish Case: Strong beats in Optical and total revenue, sustained margin expansion, and positive confirmation of Springboard progress would reinforce Corning’s position as a core AI infrastructure supplier and support a valuation re-rating.
Bearish Risk: In-line or softer results, signs of growth deceleration, or cautious guidance could spark profit-taking, particularly in a high-volatility tech environment.
Key Metrics to Watch:
- Total revenue and year-over-year growth
- Optical Communications and Enterprise Networks growth rates and margins
- Springboard annualized run-rate progress and next-quarter outlook
- Core operating margin and free cash flow
Tactical Notes: After a positive surprise with constructive long-term commentary, pullbacks may offer entry opportunities. If results are merely in line or growth momentum softens, near-term volatility risk rises and chasing strength should be avoided. Position sizing and stop levels should be adjusted according to individual risk tolerance.
Disclaimer: The above is for informational purposes only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
PE only 3x, valuation has dropped to financial crisis levels! With Samsung and SK Hynix earnings reports approaching, can they reverse the downward trend in stock prices?
Samsung Electronics and SK Hynix are facing an extreme divergence of "record-breaking profits and rock-bottom valuations," with their price-earnings ratios dropping to around 3x and foreign ownership at historic lows. Institutions believe the market is overly pessimistic, as significant profit growth for both companies over the next two years is largely secured. With this week's earnings reports, the market is focusing on management's statements regarding long-term supply outlooks and shareholder returns, in hopes that these will serve as catalysts for a revaluation of their stock prices.
A Perfect Storm for Bitcoin? Fed, PCE, GDP and Big Tech Earnings Ahead
Forex Today: Mood improves slightly to begin critical central bank week
Bitcoin Channel Breakdown — $82K Resistance, $72.5K Buy Zone: Analyst
Crypto prices
More


