
US data surpasses expectations across the board, but the US dollar and US bonds decline; bright retail figures hide concerns about consumption

Fxstreet, October 15th—— US inflation, retail, and PPI data released simultaneously: Consumption data appears strong on the surface but is weak inside, while inflation remains sticky and elevated
Several key US economic data sets were released in concentrated fashion, which were all stronger than market expectations on a data level, but market reactions and the traditional “strong data = rising dollar and US Treasury yields” logic showed a clear divergence: the US Dollar Index spiked nearly 12 points to 102.23 before sharply retreating; spot gold briefly fell $13 from $4150 to $4137 before bulls regained momentum; Treasury yields moved down simultaneously.
The market did not simply interpret the better-than-expected retail, PPI, and CPI data as an “overheating economy and a need for aggressive Fed rate hikes,” but instead is searching for recession signals hidden beneath the data—a core feature of this cycle.
Retail Sales Appear Strong but Conceal Concerns
US August retail sales rose 0.8% month-on-month, versus expectations of 0.3%; core retail sales rose 0.9% month-on-month, versus expectations of 0.5%, and annual growth remained at 6.01%, much higher than market forecasts on the surface.
However, many institutions point out that the quality of these retail figures is not high:
Much of the nominal retail value increase is due to higher prices—not higher real purchase volume. After adjusting for inflation, the real growth rate of consumption is significantly below the nominal increase, and true growth in consumer spending is weak;
Previous values were revised downward, combined with a significant softening in wage data: weekly wages declined -0.5% month-on-month and -0.1% year-on-year, turning income growth negative. The increase in consumer spending is being supported by reducing savings and borrowing more, not by rising incomes;
Energy and fuel consumption drove the total retail figure. Excluding energy, demand in discretionary consumption categories is weak.
In short: Nominal retail looks strong, real consumption is weak; this kind of resilience is not sustainable in the long run. The market is seeing not a strong economy, but households taking on debt and using up savings to cope with rising prices, with the underlying engine of consumption weakening.
While the data overall was stronger than expected, market reaction diverged from the traditional “strong data = rising dollar and UST yields” logic: the Dollar Index spiked nearly 12 points to 102.23 then quickly backtracked; spot gold dropped $13 briefly from $4150 to $4137, then bulls took control again; Treasury yields moved down in sync.
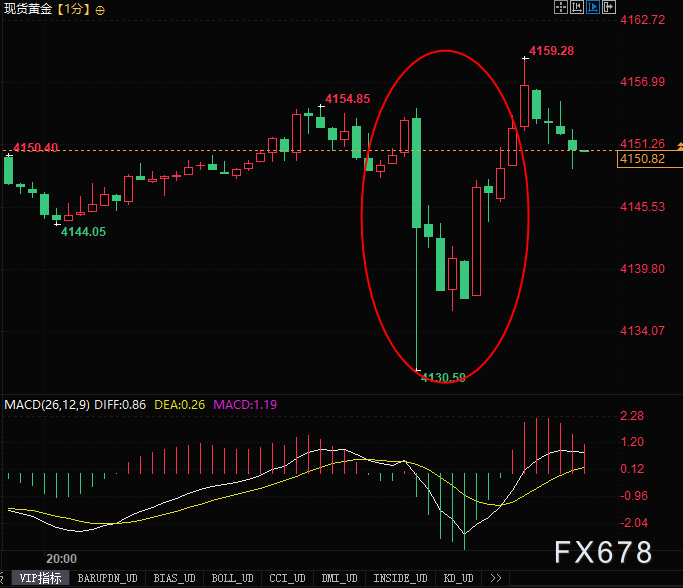
(Spot Gold, 1 Min Chart, source: Yihuitong)
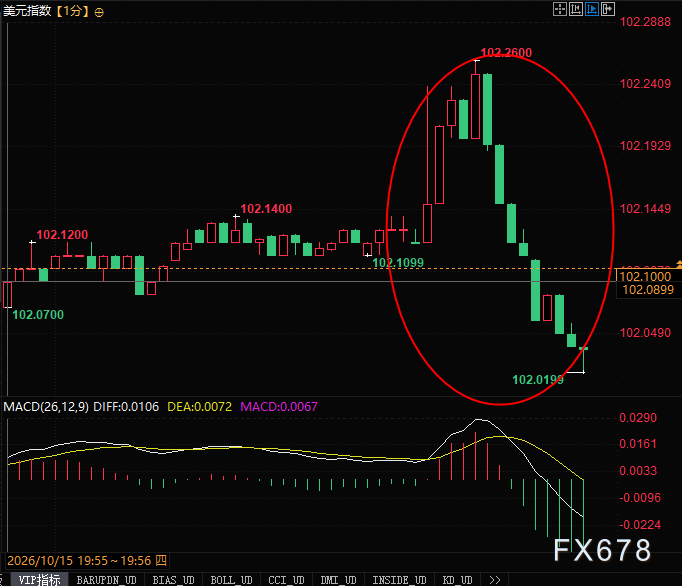
(Dollar Index, 1 Min Chart, source: Yihuitong)
PPI Shows Upstream and Downstream Inflation Simultaneous Rebound: Energy as Main Driver, Core Inflation Remains Sticky
Upstream industrial goods inflation rebounded again, indicating that downstream consumer goods price pressure is at risk of being transmitted.
Key takeaway: The source of rising inflation is primarily energy prices (external geopolitical factors), not overheated domestic consumption or wage increases. This energy-driven inflation is less sensitive to Fed rate hikes.
Labor Market Shows Signs of Cooling: Rising Prices, Nominal Incomes Turn Negative
The income side of the labor force is clearly softening: US weekly wages declined by 0.5% MoM (prior: 0.2%); weekly wages YoY fell to -0.1% (prior: 0.3%), both turning negative month-on-month and year-on-year.
Prices are rising, but nominal income for households is shrinking, eroding real purchasing power. This is the most crucial dovish signal in this data set.
The market believes lower wage growth signals a weakening of endogenous service inflation. Even if CPI rises briefly because of oil, the risk of a wage-price spiral has decreased.
Data Reshapes Fed Policy Expectations, Explains Why Dollar and Treasury Yields Fell Instead of Rising
Traditional logic: When CPI, PPI, and retail all beat expectations → Fed must keep aggressively hiking rates → Dollar and Treasury yields surge
This time, market interpretation is somewhat different:
First, inflation is caused by an external energy shock, not overheated domestic demand;
Second, retail is artificially inflated by nominal price hikes and real consumption is weakening;
Third, wage data has clearly declined and wage spiral risk has receded—this is the inflation risk Fed cares about most;
Finally, San Francisco Fed President Daly said further hikes may be needed, but there's no need for immediate action in October, indicating a generally cautious stance.
Traders judge: inflation caused by a one-off oil price surge is unlikely to force the Fed into consecutive rate hikes. Domestic demand is weakening, and the risk of a coming economic slowdown is more pressing than the short-term inflation rebound.
So, after the strong data release, the market trades on expectations of “future economic slowdown”: Treasury yields move lower, the dollar spikes then retraces, and gold quickly regains lost ground.
Conclusion: The Economy Is in a Delicate Balance, Data Shows “Strong Surface, Weaker Underneath” Characteristics
Overall, the current US economy is sending mixed signals: nominal retail, CPI, and PPI figures look impressive, but consumption growth relies on higher prices, savings, and credit. Household wages are falling and true domestic demand is lacking strength. In the short term, energy is pushing up inflation, but the core endogenous inflation driver—wages—has started cooling.
Asset pricing focus has shifted from “will inflation surge” to “when will domestic demand be dragged down by high rates and falling incomes.” Focus for the future: the pace of savings depletion, credit card delinquencies, and whether fourth-quarter consumption shows a significant pullback.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Jacob Metzger stops buying XRP after hitting target, sets $1,000 price goal for 2030
XRP ETFs net $1.8 billion in 13 weeks, price lags despite Wall Street inflows
Raydium, Zcash and altcoins drop over 12% as crypto market slides 3.7%
Crypto prices
More


