Bitget App
Trade smarter
Buy cryptoMarketsTradeFuturesStocksEarnInstitutionAI & More
Bitcoin Price Forecast: Rainbow Chart Highlights October 31 $1.36M Target

Bitcoin Price Forecast: Rainbow Chart Highlights October 31 $1.36M Target

CoinspeakerCoinspeaker2026/10/04 21:27
By:Coinspeaker

The Bitcoin price forecast long-term valuation model, the Rainbow Chart, suggests that the cryptocurrency remains below its historical trend valuation as October begins. The outlook comes as Bitcoin failed to reclaim the $90,000 level, a move that could have opened the door to a push toward six-figure valuations.

At press time, Bitcoin was trading at $84,584, while remaining above its 50-day SMA of $78,136 and 200-day SMA of $71,404, indicating the broader uptrend remains intact.
Bitcoin Price Forecast: Rainbow Chart Highlights October 31 $1.36M Target image 0

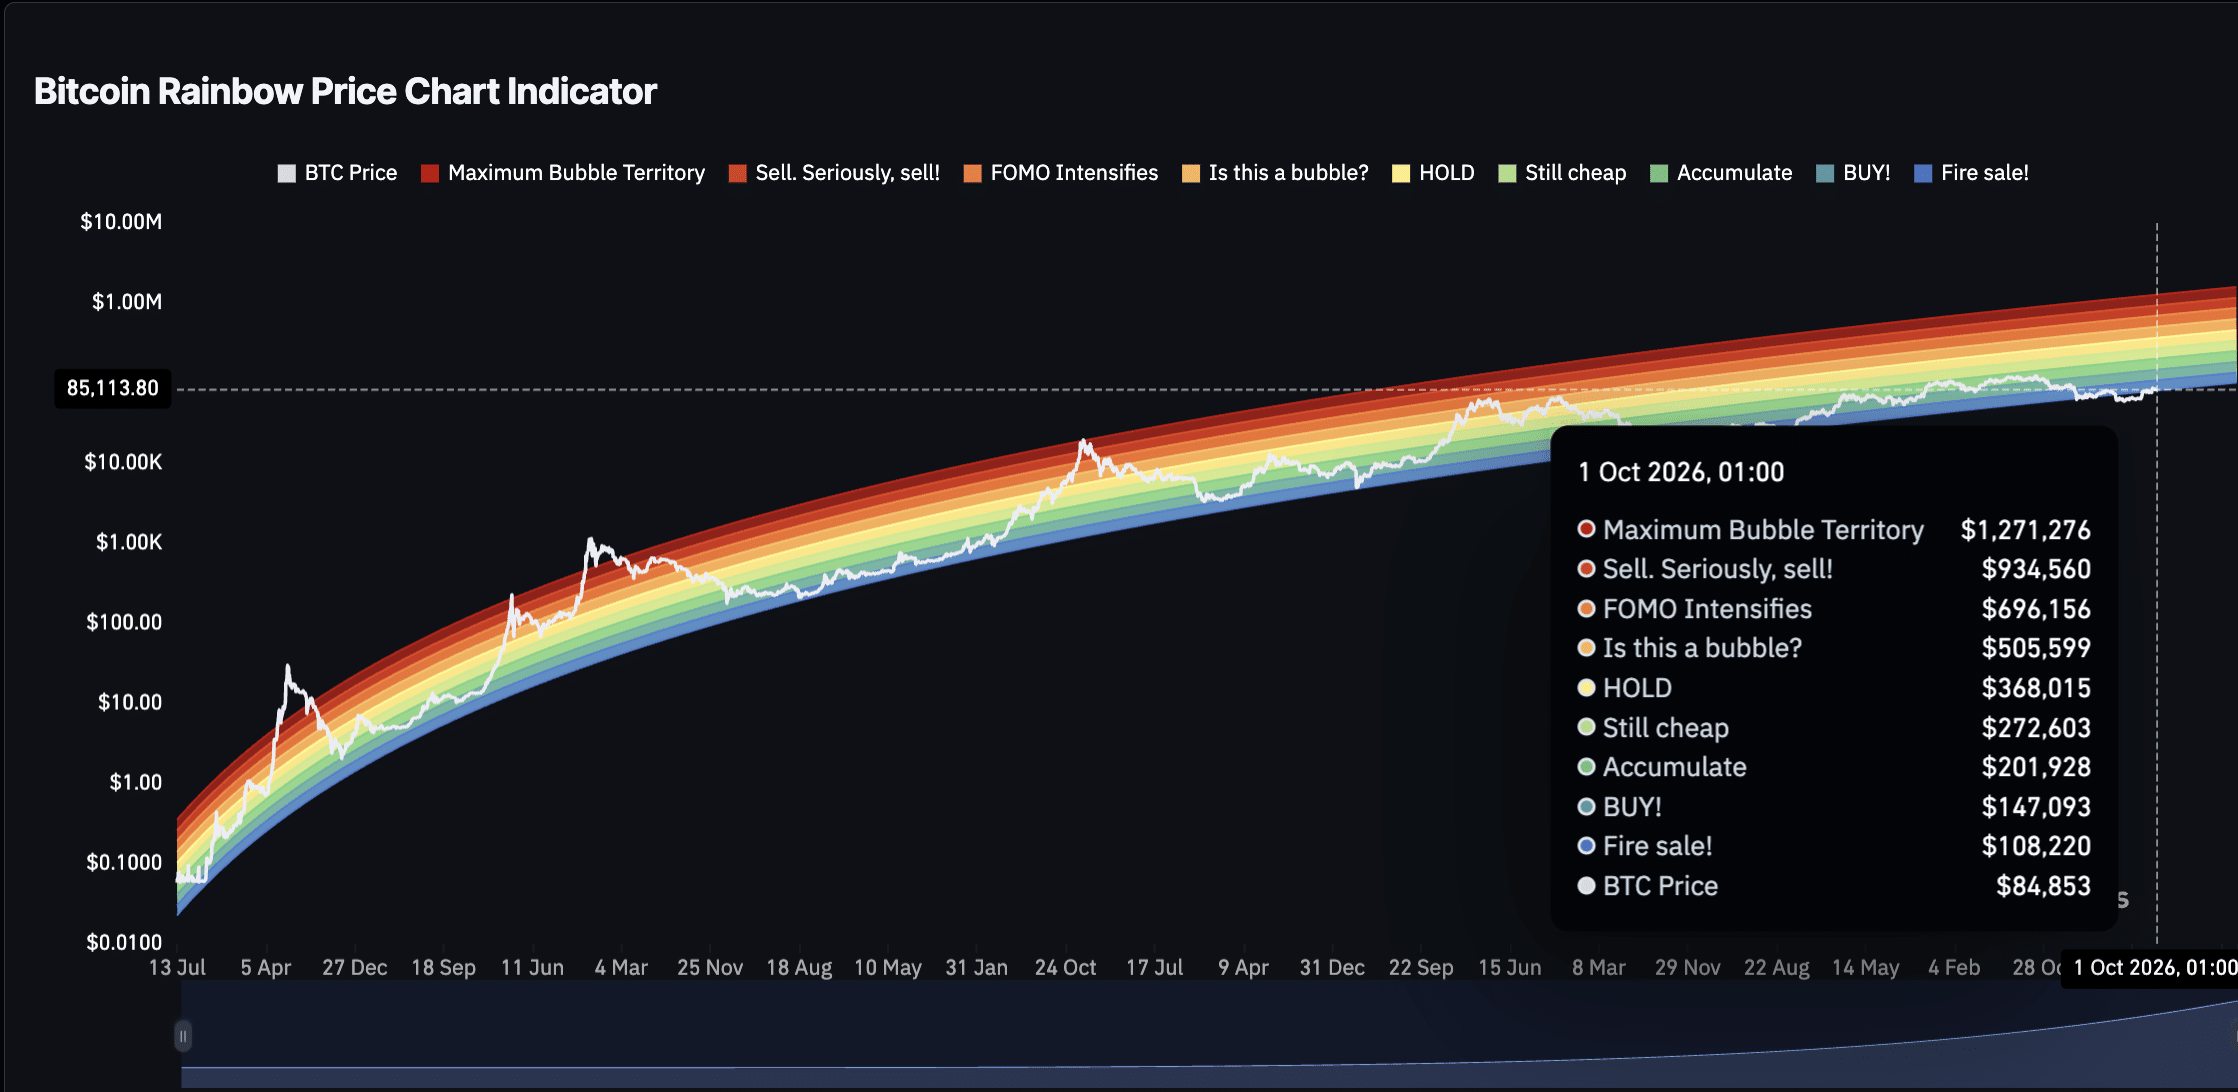
Although the Rainbow Chart’s October 31 valuation bands sit well above Bitcoin’s current price, the indicator is designed to gauge long-term valuation rather than forecast where $BTC will trade by month-end.

According to the chart, the highest valuation zone on October 31 is ‘Maximum Bubble Territory’ at $1.36M, a band historically associated with extreme market euphoria and cycle tops, a position we aren’t yet in.

What Does the Rainbow Chart Say About Bitcoin for October and Beyond?

Below, the ‘Sell. Seriously, SELL!’ zone is marked at $998,844, which corresponds to historically high valuations and increased profit-taking. The ‘FOMO Intensifies’ band is set at $733,467, indicating periods when speculative demand tends to rise.

Next is the ‘Is this a bubble?’ level at $547,041, followed by the ‘HODL!’ zone at $396,987, which is generally regarded as fair value. The ‘Still cheap’ band is positioned at $287,747, while ‘Accumulate’ is at $209,292, both suggesting undervaluation relative to Bitcoin’s long-term trend.

The ‘BUY!’ band is established at $153,802, representing significant undervaluation. The lowest band, ‘Basically a Fire Sale,’ is found at $115,355, a zone historically linked to deep discounts and extreme market pessimism.

Currently, Bitcoin is trading around $85,000, below the chart’s lowest valuation band. This highlights the discrepancy between current market prices and the model’s long-term trajectory.

Bitcoin Short-Term Price Forecast

While the Rainbow Chart mostly focuses on long-term valuation, Bitcoin’s recent rally toward $87,000 stalled in the short term after whales reportedly took profits on more than 30,000 BTC. The $87,000 region also coincided with the upper boundary of a trading channel that has capped prices for more than two weeks.

Not only were whales taking profits on the way up, selling more than 30,000 BTC, but $87,000 also marked the top of the channel that has rejected Bitcoin on multiple occasions.

After the rejection, $82,500 is the immediate downside target. The argument is that if Bitcoin falls to that level and whale accumulation resumes, it could confirm another rebound attempt toward $87,000.

It is highly unlikely that the Rainbow Chart’s Bitcoin Price Forecast of $1.36M by October 31 will come to fruition; however, that chart is merely a tool to show what prices could look like under different market structures.

Bitcoin Hyper (HYPER): Scaling the King of Crypto via Solana’s Virtual Machine
Bitcoin Price Forecast: Rainbow Chart Highlights October 31 $1.36M Target image 1

Bitcoin Hyper (HYPER) is an upcoming Layer 2 blockchain on the Solana Virtual Machine (SVM) that settles directly to the Bitcoin mainnet.

Through a non-custodial canonical bridge, users can lock their BTC and mint wrapped Bitcoin on the L2, enabling near-instant finality for DeFi, NFTs, and other decentralized applications. The SVM periodically anchors transaction batches to the Bitcoin blockchain for security.

The native HYPER token is used for network gas fees, staking, governance, and premium features, with a total supply capped at 21 billion tokens. Allocations include 30% for development, 25% for treasury, and 20% for marketing.

The mainnet launch is set for Q4 2026 and will include the canonical bridge, ecosystem dApps, and exchange listings.

0
0

Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.

Understand the market, then trade.
Bitget offers one-stop trading for cryptocurrencies, stocks, and gold.
Trade now!

You may also like

If US Treasury yields continue to rise, what will Washington do next?

The Treasury has maintained liquidity by increasing the issuance of short-term Treasury bills and conducting small-scale buybacks. Some advocate for reducing expenditures to address the debt burden. Political constraints tilt the risk toward inflation, which harms bondholders' interests. Karen Brettell, Reuters, October 5 - The cost of borrowing for the U.S. government is rising, while it has almost exhausted straightforward ways to control those costs. Long-term Treasury yields are now near their highest levels in two decades, and the causes don't appear to be temporary. Washington is issuing large amounts of government debt to cover a fiscal deficit that shows no signs of shrinking. Inflation is cooling only slowly. Moreover, while the real estate and automotive sectors are struggling, the artificial intelligence investment boom is keeping the economy robust enough to prevent interest rates from falling. As a result, with over $40 trillion in debt, annual interest payments alone amount to around $1 trillion. Washington has options, from relying more on short-term borrowing to, in the most extreme case, having the Federal Reserve cap long-term yields. The more policymakers resort to such measures, the higher the risk of fueling inflation, potentially causing more pain for bondholders in the future. Torsten Slok, Chief Economist at Apollo Global Management, noted that for every $5 the government collects in taxes, $1 goes to service the debt. "That's a very, very high number, and it's only going to grow." U.S. President Donald Trump said in a September 28 interview with Time magazine that debt can be repaid through economic growth or inflation. But if these methods fail, the Treasury has other options ranging from moderate to radical. At present, the Treasury is increasingly relying on issuing short-term bills and conducting small-scale buybacks of old debt to help boost market liquidity. In a worse scenario, the next step would require Fed intervention. One method is large-scale purchases of long-term bonds, akin to 1961's "Operation Twist", another is directly capping long-term yields—a measure not used by the U.S. since World War II. The more aggressive the measures, the more they can suppress rates, but also the greater the risk of spurring inflation. “We are getting to a point where it's clear the government is uncomfortable with current rate levels," said Jeffrey Gundlach, CEO of DoubleLine Capital, at a recent investment event. Operation Twist Historically, the next escalation would likely be a full-scale reactivation of "Operation Twist." Launched in 1961, this strategy involved selling short-term Treasuries and purchasing long-term ones to flatten the yield curve. Implementing a substantial twist would require the Fed's assistance, but the Fed may stand pat unless there is an obvious financial emergency. Slok said that without the Fed's balance sheet, the Treasury has very limited tools for lowering rates. However, Fed Chair Kevin Warsh has criticized holding large amounts of government debt and other securities, arguing that massive bond buying blurs the line between monetary policy and government debt management. He has called for a new agreement between the Treasury and the Fed, under which the Fed Chair and Treasury Secretary would communicate publicly about the Fed's balance sheet and the Treasury’s debt issuance plans. Yield Curve Control If Operation Twist–style purchases don't work, the next move would be explicit yield curve control. In this scenario, the central bank commits to buying an unlimited amount of government debt to keep long-term rates under a set cap. From 1942 until the 1951 Treasury-Fed Accord, the Fed capped long-term Treasury yields at 2.5% to help fund WWII and the postwar recovery. The Bank of Japan implemented a version of this policy from 2016 to 2024. By artificially lowering rates, yield curve control can ease the political pressure of fiscal deficits. But it only works as long as investors aren't worried about being repaid with dollars devalued by inflation. Once that confidence is shaken, bond-buying meant to suppress rates only fuels the inflation it's designed to conceal. Veronique de Rugy, Senior Research Fellow at the Mercatus Center at George Mason University, said that ultimately, the only way to solve the debt problem is by cutting expenditures. “Congress needs to implement fiscal consolidation—in other words, austerity. The Fed cannot do this alone.” Divergent Paths John Higgins, Chief Economic Advisor at Capital Economics, notes that since World War II, the U.S. has only significantly reduced its debt-to-GDP ratio twice, but bondholders' experiences differed substantially each time. After the war, the debt-to-GDP ratio fell from about 106% in 1946 to 23% in 1974, while the 10-year Treasury yield climbed from 2.2% to 7.5%. In the 1990s, the ratio declined from 48% to 32%, and yields fell as well. What made the difference? After WWII, restr

路透社•2026/10/05 10:11