
BlackBerry Q2 Earnings Preview: Can QNX Offset a Secure Communications Air Pocket
 2026/09/23 03:45
- Investment Snapshot
BlackBerry (BB.US) will report fiscal 2027 second-quarter results before the U.S. market open on September 24, 2026, with the conference call at 8:00 a.m. ET. Company guidance calls for revenue of $137–$148 million, versus Wall Street consensus of about $143–$146 million, implying roughly (+10% to +12% YoY) against $129.6 million a year ago. Non-GAAP EPS guidance is $0.03–$0.04, with consensus at the high end of $0.04 (flat YoY).
Last quarter the company posted revenue of $152.9 million (+26.0% YoY) and adjusted EPS of $0.04, beating on both lines and raising the full-year outlook. The stock jumped about 20% the next session, then faded from those highs. The setup this quarter is straightforward: whether QNX can sustain high-quality growth, and how far Secure Communications normalizes after a large Canadian government deal pulled demand forward.
- Four Things to Watch
Focus 1: QNX growth quality — can development licenses reconfirm the royalty pipeline
QNX is the valuation anchor. In Q1 the segment delivered $72.3 million (+26.0% YoY), with adjusted gross margin at 86%. Development licenses hit an eight-quarter high, and the royalty backlog is close to $1 billion. Q2 QNX guidance is $70–$75 million in revenue and $16–$21 million in adjusted EBITDA.
The market is less focused on growth for its own sake than on mix: whether development licenses stay strong, royalties keep pace, and general embedded markets (industrial, robotics, medical) can offset auto-cycle risk. A print near the high end with firm license revenue would support multi-year cash visibility. A beat driven mainly by one-off services would raise questions about growth quality.
Focus 2: The Secure Communications sequential drop — normal air pocket or softer demand
Secure Communications revenue was $73.6 million in Q1 (about +24.0% YoY), helped by the expansion and multi-year extension of the Shared Services Canada agreement. Management has already said large government deals do not close every quarter. Q2 guidance drops sharply to $57–$63 million, with adjusted EBITDA of only $5–$10 million.
The tell is recurring-revenue durability. Q1 ARR was about $220 million (more than +5% YoY) and dollar-based net retention (DBNRR) was 92%. A result at the high end of the range with stable-to-improving retention would look like timing. A miss below $57 million or further retention slippage could force a rethink of government-order sustainability.
Focus 3: Margins and cash — digestion quarter or earnings step-down
Company-level Q2 adjusted EBITDA is guided to $20–$30 million, with operating cash flow from breakeven to $10 million, well below Q1 adjusted EBITDA of $36.3 million (+144.0% YoY). Licensing guidance was raised to about $10 million, versus $6.6 million a year ago, which offers some cushion.
QNX’s high incremental margin is the medium-term leverage. If total revenue comes in toward the high end and QNX mix improves, EBITDA can drift toward $30 million. If mix shifts toward lower-margin Secure Communications or costs rebound, the tape may get a “revenue okay, profit light” print — a difficult combination for a high-beta name.
Focus 4: Defending full-year guidance and the Physical AI narrative
Full-year guidance remains revenue of $594–$621 million, adjusted EBITDA of $119–$139 million, non-GAAP EPS of $0.16–$0.20, and operating cash flow of about $100 million. That outlook was already raised after Q1, so the bar this quarter is “hold or raise,” not another easy beat-and-raise.
The call will also be parsed for an Alloy Kore design win, Physical AI / robotics commentary, and whether QNX’s Hailo and other edge-accelerator work is turning into measurable orders. These efforts are still early and will not move the P&L much this quarter, but tone will influence the growth premium.
- Risks and Opportunities
Upside catalysts:
- QNX revenue near or above $75 million, with development licenses and royalties both firm, reinforcing multi-year visibility.
- Secure Communications better than the midpoint, with ARR and the 92% retention rate no longer rolling over — evidence that the Q1 deal did not steal from future quarters.
- Adjusted EBITDA near $30 million, plus a reiteration or modest raise of full-year revenue and EBITDA.
Downside risks:
- Total revenue near the $137 million low end, QNX deceleration, and a fade in development licenses.
- Secure Communications below $57 million, or further retention weakness, raising doubts about government demand.
- An in-line print with cautious Alloy Kore / Physical AI commentary, against a stock that has already pulled back from its post-Q1 spike, inviting profit-taking.
- Trading Framework
Bull case: QNX mix is healthy (licenses plus royalties), the Secure Communications drop is smaller than feared, EBITDA and cash land in the top half of guidance, and management holds the full-year outlook. That reads as digestion, not a fundamental turn, and can support a sentiment reset.
Bear case: Revenue and profit merely scrape by, QNX quality is average, the Secure Communications air pocket is read as demand, or full-year guidance is left unchanged. The company has beaten in each of the past four quarters (average surprise about 94.6% on the Zacks measure). The market is already paying for another beat; a merely in-line result can still pressure the multiple.
Key numbers:
- Total revenue and YoY growth versus the roughly $143 million guidance midpoint
- QNX revenue and the license / royalty mix
- Secure Communications revenue, ARR, and DBNRR
- Adjusted EBITDA, operating cash flow, and any change to full-year guidance
How to use it: If results and guidance are both strong, wait for the opening spike to fade before reassessing. If the print is only in line or Secure Communications is clearly weak, expect wider pre-market and regular-session swings and avoid chasing. Size and stops should match personal risk tolerance.
Trading levels (based on the recent range):
- Long zone: $8.40–$8.50; a break of $9.00–$9.20 opens room higher
- Reduce / short zone: $9.00–$9.20
- Below $8.00, respect downside risk
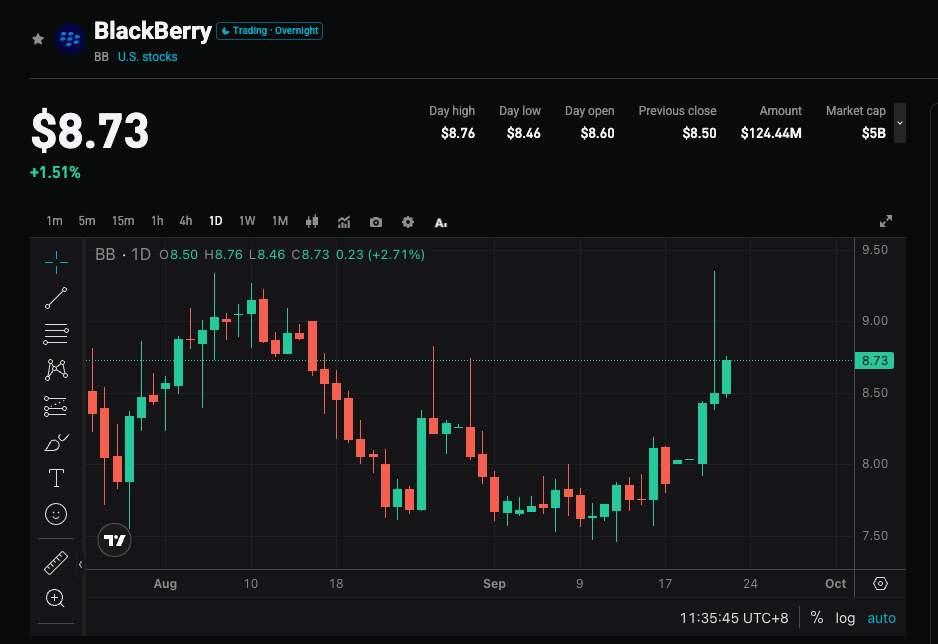
Tactical notes (BB, as of the September 22 close at $8.62):
- Into the print: The stock bounced from the $8.00–$8.15 shelf, tagged $9.22 intraday, and closed at $8.62. The 50-day average near $8.70 sits under the $9.00–$9.20 resistance band. Event risk/reward is only average. Implied move is about ±9% (roughly $7.85–$9.40). Keep event exposure light. Avoid leveraged longs below $8.00.
- Long structure: Close back above $9.00–$9.20 and hold $8.40–$8.50 on a retest. Upside references: $10.00 / $10.30. Stops can sit at $8.20, or below $8.00 if risk tolerance allows a wider buffer.
- Short / hedge structure: A gap that cannot reclaim $8.40–$8.50, or a failed push through $9.00–$9.20. Downside references: $8.00 / $7.50 / $6.10.
Disclaimer: For reference only. This is not investment advice.
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Top Trending Cryptocurrencies Today: PENGU and PRL Surge as EDEL Falls
X-Art turns XRP Ledger’s creation into sitcom parody with “The One Without Mining”
US Stocks Lower Pre-Bell as Traders Await Chinese President's US Visit, Monitor Iran War Developments
KB Home Lowers Full-Year Housing Gross Profit Margin Guidance; Shares Down Pre-Bell
Crypto prices
More


