
Bitcoin price tracking ahead of the past 2 halvings — now 3 months to go

If you expected spot ETFs to pump the price of bitcoin, chances are you’ll love what the halving is meant to do
Bitcoin ETFs haven’t yet summoned a tidal wave of fresh capital to crypto markets, but fret not. The next supposed price catalyst, the bitcoin halving, is right around the corner.
Legend has it that bitcoin halvings are monstrously bullish. After all, the last three bull markets each began roaring only a few months after each event.
There have only been three halvings in Bitcoin’s history, in 2012, 2016 and 2020, and three is far too small a sample size from which to draw any meaningful conclusion.
Still, fewer bitcoins released each day will lead to a supply crunch, believers would say, inevitably pushing bitcoin ( BTC ) skyhigh.
Truth is, nobody really knows what will happen around the halving, but it’s the bitcoin miners who will feel its immediate effects.
Bitcoin distributes all new bitcoins directly to miners, who in about three months (around April 19) will suddenly earn 50% fewer block rewards: 3.125 BTC ($135,000) per block down from 6.25 BTC ($270,000).
- Bitcoin self-regulates the time between blocks, keeping it around 10 minutes on average.
- Miners usually solve 144 blocks in a 24-hour period, which won’t change after the halving.
- Block rewards currently add up to 900 BTC ($38.9 million) each day.
Miners can sell the bitcoin they earn to cover overheads (mostly electricity and in some cases debt ). Bitcoin users also pad out block rewards with transaction fees, and thanks to the popularity of Ordinals inscriptions , they’re forking out more than ever to use the network.
Users altogether paid about $500,000 per day in October but as much as $24 million in December, although miners have earned under $10 million per day in January so far.
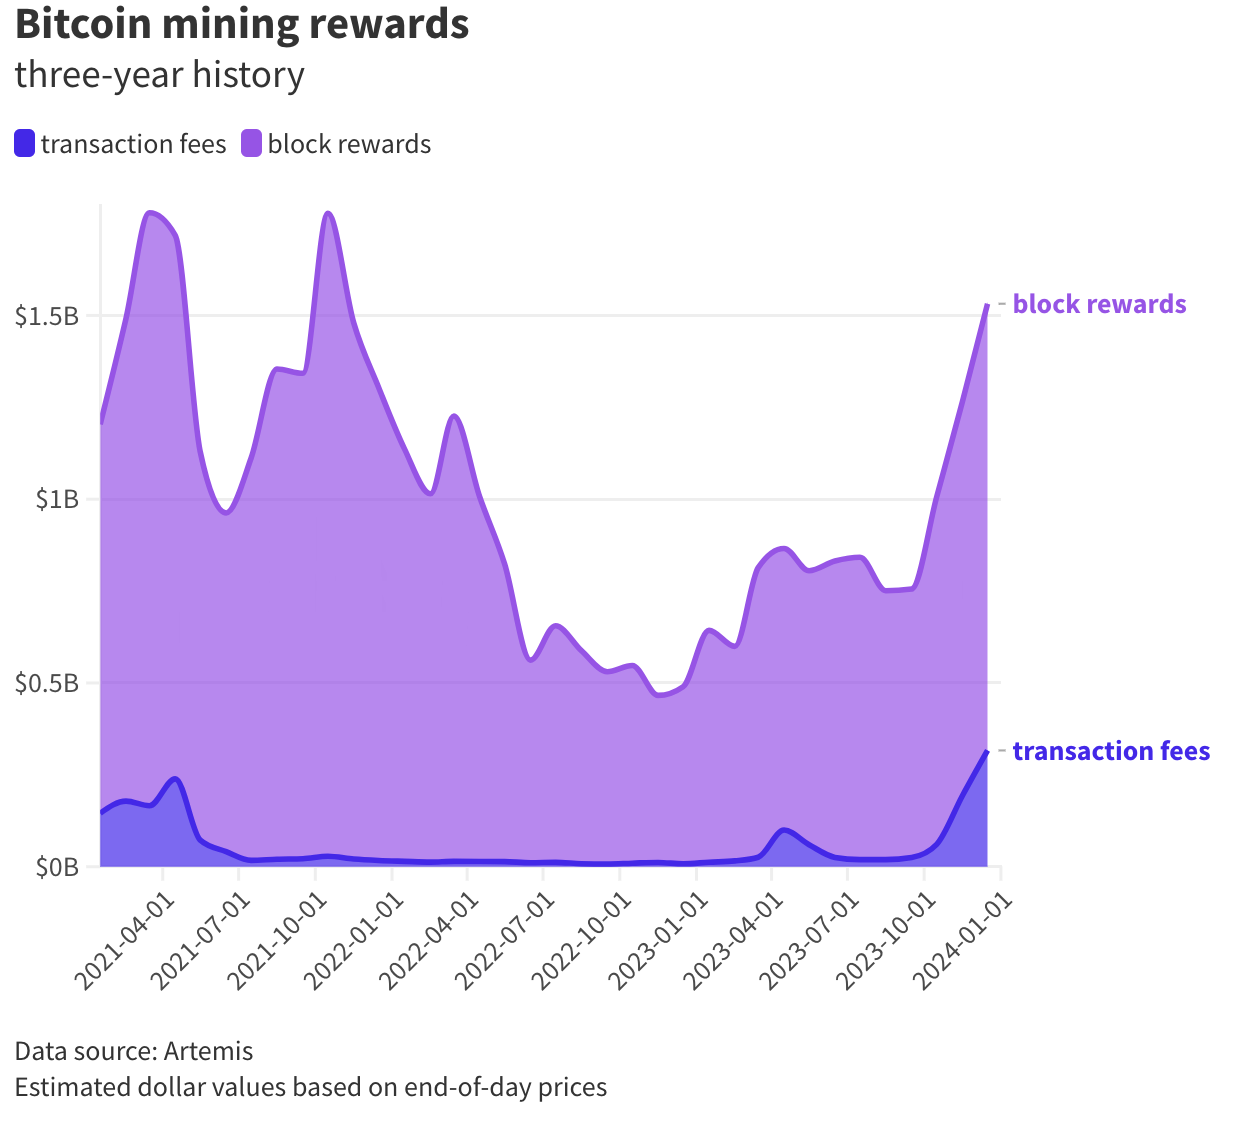
That still works out to be about half the block rewards up for grabs after April 19. But bitcoin’s price would need to stay about the same until then, alongside consistent demand for inscriptions.
Bitcoin staying up would solve halving concerns
All this makes bitcoin’s price a very sensitive issue for the network .
It’s always possible that the price of bitcoin could drop so low that it would force miners to switch off their rigs lest they run at a loss — a common occurrence throughout the last two bear markets, leading to debt raises and a string of bankruptcies .
One estimate from Glassnode last September suggested that bitcoin dropping to $30,200 would “likely put the majority of the mining market into severe income stress.” Bitcoin trades for $43,000 right now, which would mean bitcoin miners could hypothetically withstand a 30% drop in bitcoin’s price around the next halving .
Glassnode’s calculation was done weeks before Ordinals inspired a gigantic boom in fees, so it’s likely miners will have more breathing room than first anticipated.
(There’s also far more hashrate on the Bitcoin network than ever before and its overall security is unlikely to be significantly impacted even if a large percentage of miners were to be switched off for any reason.)
Block rewards are paid in bitcoin and are unaffected by its US dollar value. So, the opposite scenario, in which the price of bitcoin pumps significantly around the halving is, of course, much better for miners and everyone else.
Any concerns over whether block rewards will be enough to keep miners afloat after the halving could be properly put to bed if bitcoin’s price were to simply double.
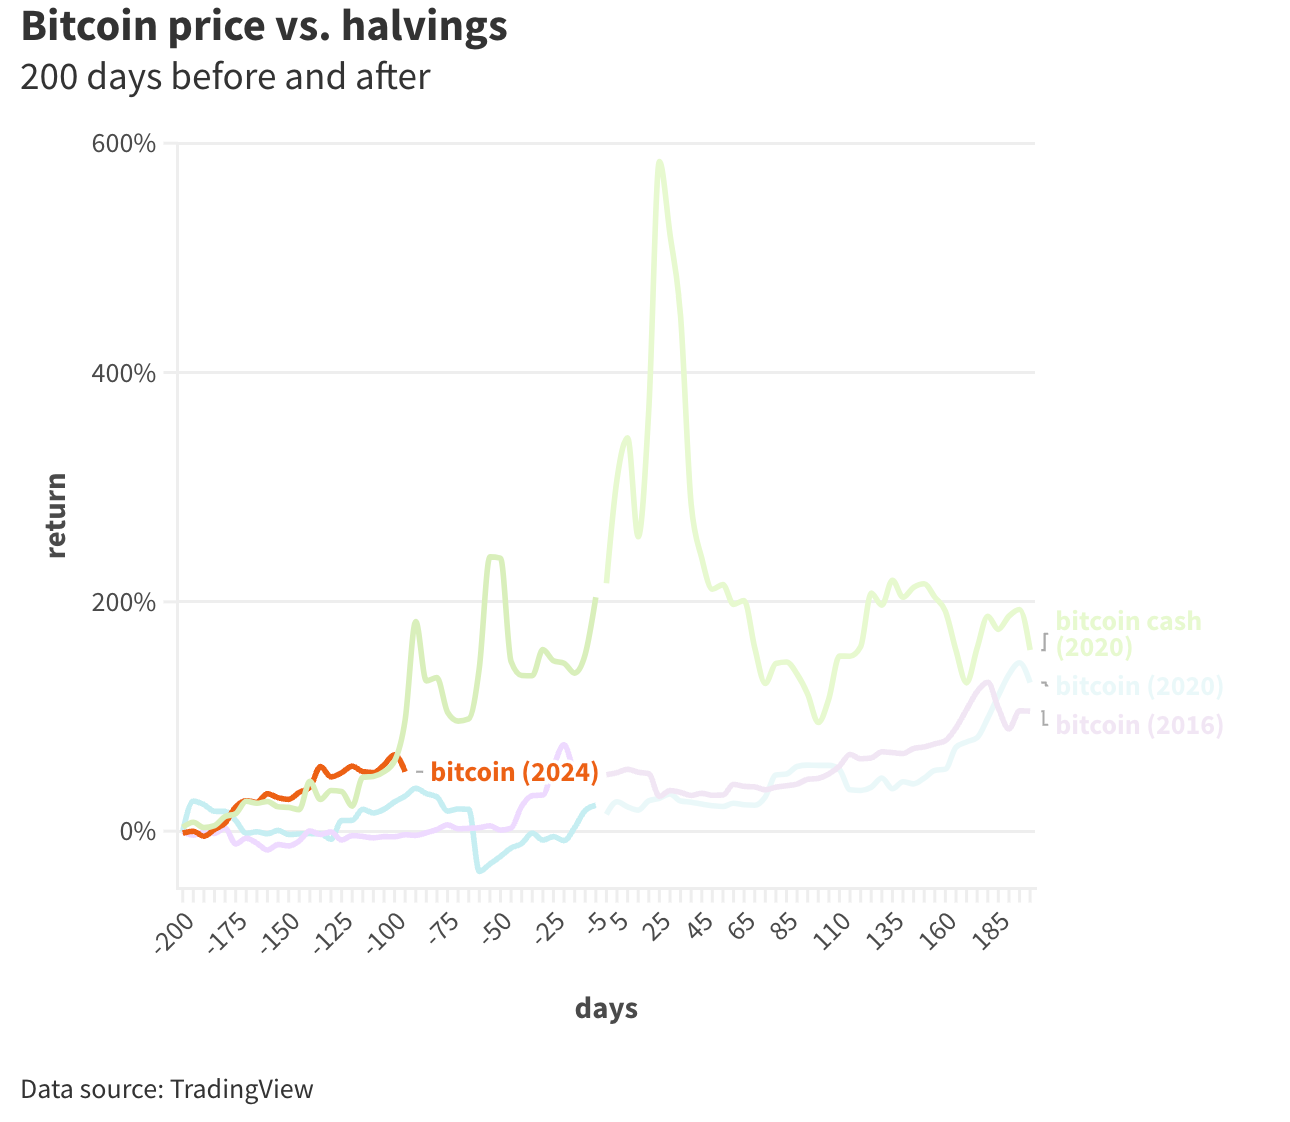
So far, so good. Tracking prices 200 days out from the past three bitcoin halvings shows BTC already rallying by 50% until now, largely propelled by buzz around BlackRock and others’ bitcoin ETF bids.
That’s better than the lead up to the past two halvings. Bitcoin had jumped by less than one third by this point before the 2020 halving, and in 2016, bitcoin had fallen 3%.
Bitcoin’s performance around the first halving in 2012 blows the others out of the water. BTC rallied nearly 150% in the 200 days leading up to the event. Including the 200 days after stretches that number up to 4,500%.
Bitcoin is just as likely to map how its biggest fork, bitcoin cash ( BCH ), performed around its own halving.
BCH tripled in the 200 days leading up to it and tripled again in the month after — but would go on to collapse by two-thirds over the following weeks.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
The US market narrative undergoes a "dramatic reversal": shifting from "AI-driven deflation and controllable US debt" to "AI squeezing the bond market, and Bassen unable to control long-term interest rates"
Deutsche Bank points out that the market narrative regarding the U.S. economy has shifted from "AI drives down inflation" to "AI-related bond issuance pushes up U.S. Treasury yields," but pessimism may be overdone. The bank believes that the real risks underestimated by the market are security incidents in the AI ecosystem, failed IPOs, or underwhelming revenues, which could undermine the dollar and support the bond market. In addition, France's fiscal difficulties are putting new pressure on the euro.

Deutsche Bank: The "fifth wave of tech stock rally" in US stocks since late July has peaked, prepare for a "V-shaped reversal"
Deutsche Bank has downgraded its rating on US technology stocks from overweight to neutral, noting that the fifth round of tech stock rally since July 29 is approaching the upper boundary of the long-term trend channel. The current upside potential is only about 4 percentage points, while historical trends indicate downside risks could reach 16 percentage points. Funds are expected to rotate into other sectors, and the European market, with its lower tech exposure, is likely to benefit relatively. However, Deutsche Bank emphasized that the long-term outperformance trend of technology stocks remains unchanged.
How expensive is AI computing power rental in the US? "Spot price" is twice that of long-term contracts, and four times the return threshold for cloud service providers.
The short-term spot leasing price for AI computing power reaches as high as $40 to $50 billion per gigawatt per year, while the price for long-term contracts is only $20 billion per year, and the breakeven threshold for supercomputing cloud operators is around $12 billion per year. However, according to Goldman Sachs, the fundamental reason why hyperscale cloud providers like Google rent computing power at such significant premiums is that their in-house capacity cannot keep up; once their own capacity catches up, the spot premium will disappear.

Crypto prices
More


