JPMorgan (JPM) Q3 Earnings Preview: Testing Resilience in Investment Banking and Trading Amid High Base
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
1. Investment Highlights
JPMorgan is scheduled to report its fiscal 2026 third-quarter results before the U.S. market open on October 13, 2026. Wall Street consensus expects revenue of approximately $51.19 billion (+10.3% YoY) and adjusted EPS of about $5.90 (+16.4% YoY). In the year-ago period, revenue was $46.43 billion and EPS was $5.07. Management has previously guided that investment banking fees and Markets revenue are both expected to grow in the mid-to-high teens year over year. Against a backdrop of elevated volatility in the banking sector, the market will focus on whether core businesses can continue to beat expectations after a high base, the stability of net interest income, and trends in credit quality and expense control.
Focus 1: Can Total Revenue and EPS Extend the Beat Streak
JPMorgan has a long track record of beating estimates. Q2 already delivered a significant beat (revenue of $57.35 billion, EPS of $7.70), and current expectations are relatively moderate. A clear beat versus consensus, accompanied by constructive commentary, would further validate the firm’s earnings resilience across rate and market environments and support valuation recovery.
Focus 2: Delivery of Mid-to-High Teens Growth in Investment Banking and Markets
Management has guided that Q3 investment banking fees and Markets revenue are both expected to rise in the mid-to-high teens year over year. In Q2, Markets revenue reached $12.1 billion (+35% YoY). Although global M&A activity has slowed, the firm has emphasized that its pipeline remains strong with broad-based growth across products and geographies. Performance in these businesses will be a key determinant of non-interest income quality and market confidence in the durability of its Wall Street franchise.
Focus 3: Net Interest Income (NII) Stability and Full-Year Guidance
Q2 NII was $25.6 billion (+10% YoY), or $23.7 billion excluding Markets (+4% YoY). Investors will watch the impact of deposit costs, loan growth, and the rate environment on net interest margins. Stable NII with an upgrade to full-year guidance would reinforce the firm’s core banking earnings floor; any signs of pressure could raise concerns about slowing growth.
Focus 4: Credit Quality and Expense Control
Credit provisions and non-performing loan trends remain critical for bank stocks. Credit costs were manageable in Q2, but the market will monitor any marginal deterioration in consumer or commercial credit. At the same time, whether expenses—particularly performance-related compensation tied to strong trading activity—remain controlled will affect profitability and capital return expectations.
3. Risks and Opportunities
Upside Catalysts:
- Total revenue and EPS meaningfully exceed consensus, with an upgrade to full-year NII or core business guidance.
- Investment banking fees and Markets revenue grow at or above the mid-to-high teens, confirming resilience in trading and deal activity.
- Credit costs come in below expectations, NII remains stable, and expense control is solid.
Downside Risks:
- Results merely meet or slightly miss consensus, with growth momentum slowing off a high base.
- Markets or investment banking revenue falls short of the guided range, or the pipeline shows signs of softening.
- Credit provisions rise or NII comes under pressure, accompanied by higher-than-expected expenses.
4. Trading Strategy Considerations
Bull Case: A clear beat on core metrics combined with constructive commentary on NII, investment banking, and trading would strengthen confidence in JPMorgan’s earnings quality and capital returns, supporting a recovery in the stock.
Bear Case: In-line or soft results, cautious guidance, or rising credit costs could trigger profit-taking, particularly amid heightened volatility across the banking sector.
Key Metrics to Watch:
- Total revenue and year-over-year growth
- Investment banking fees and Markets revenue performance
- Net interest income (with and without Markets) and full-year guidance
- Credit provisions and non-performing loan trends
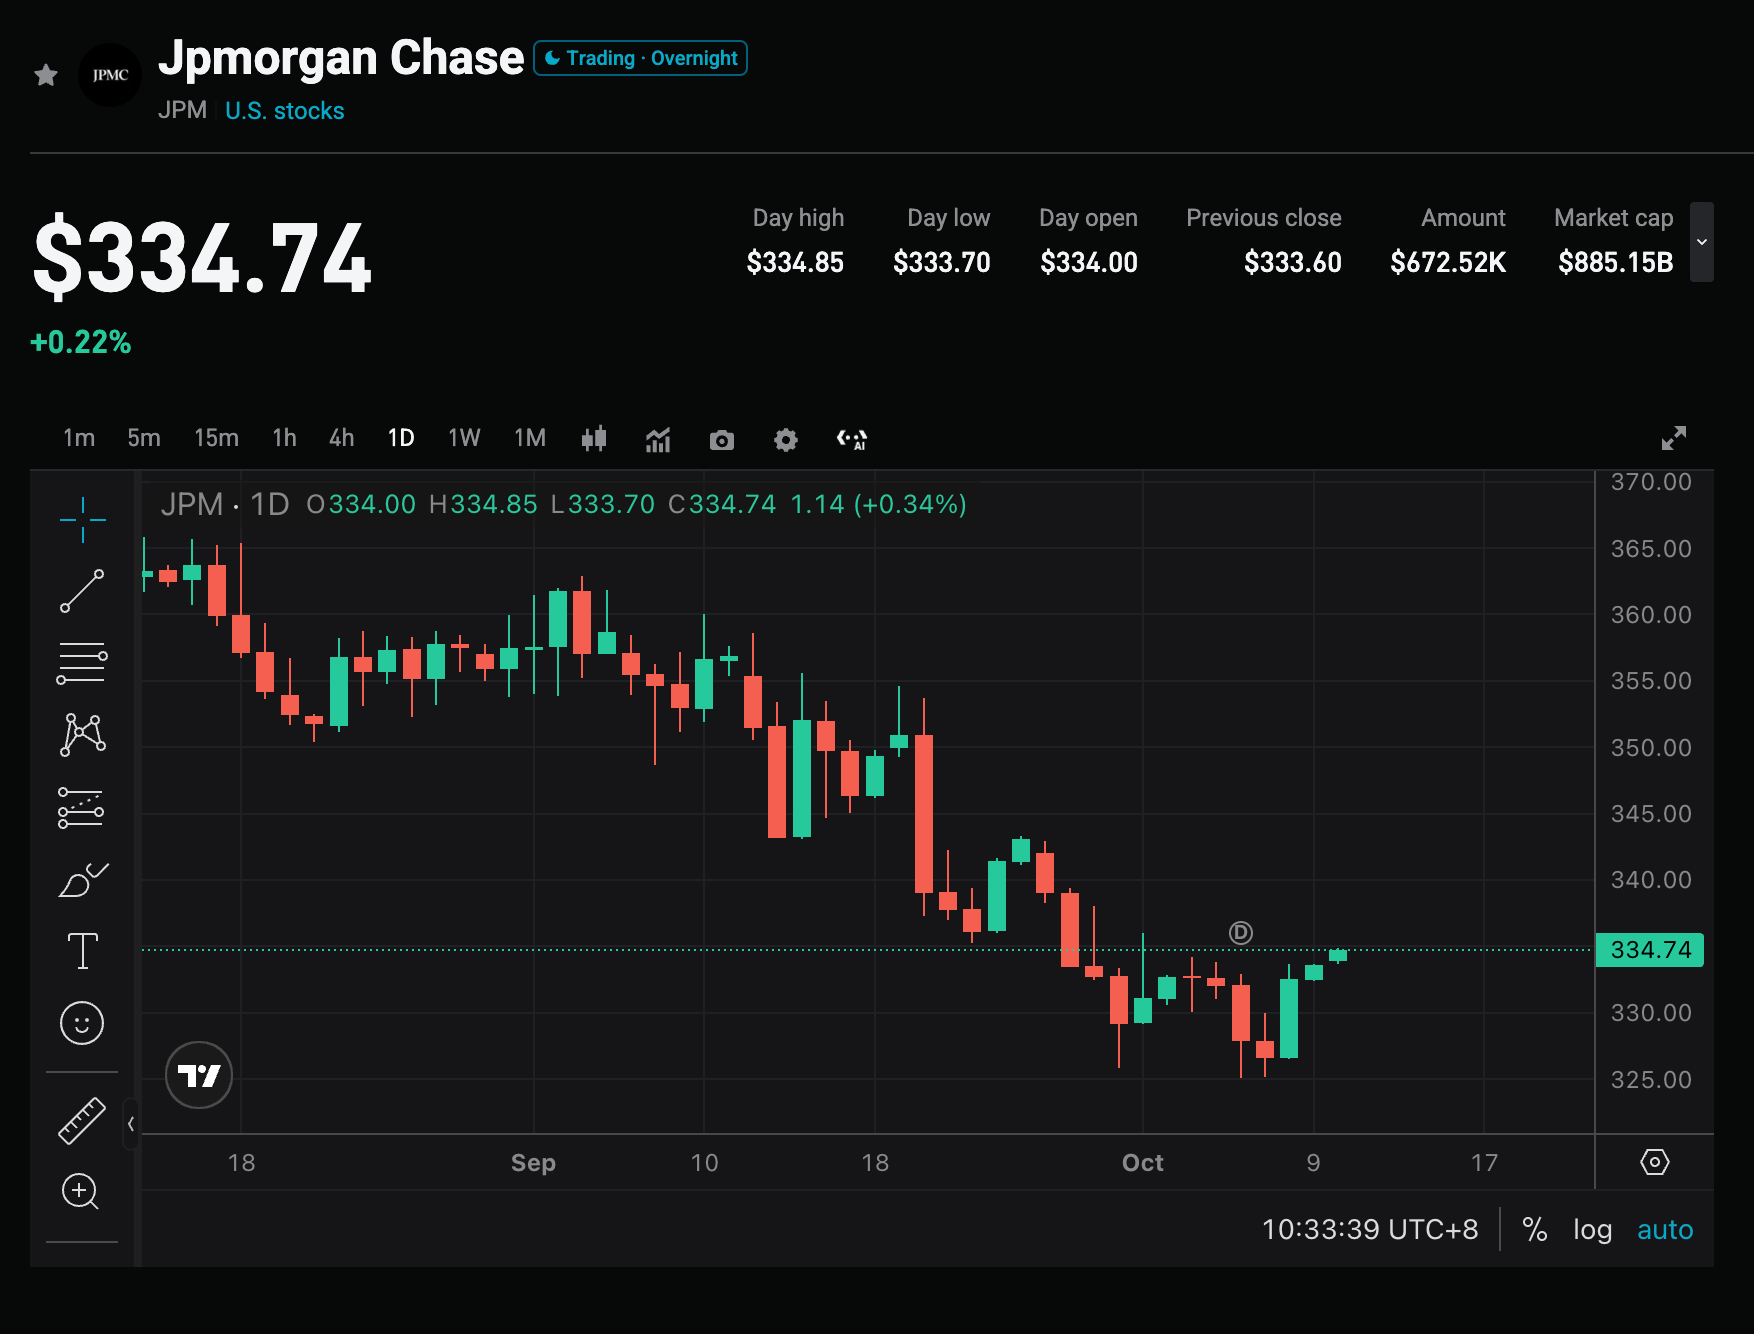
Tactical Notes (as of October 9 close at $332.99):
- Pre-Earnings: The stock has pulled back from the late-September highs around 355–360 and has recently traded in the 325–334 range, closing at 332.99 on October 9. The 50-day moving average near 350 acts as clear overhead resistance, while the 200-day moving average near 322 provides support below. The pre-event risk-reward is neutral. Options imply a move of roughly ±3.1% to ±3.6% (approximately 321–345). Keep position size light ahead of the event and avoid adding leveraged long exposure below 325.
- Bullish Structure: A close back above 340–345 with a successful retest of 330–332. Upside reference levels: 350 / 360. Stop can be placed at 325, or lowered toward the 320 area (near the 200-day moving average) depending on risk tolerance.
- Bearish / Hedge Structure: Failure to reclaim 330–332 after a gap down, or a failed push through 340. Downside reference levels: 325 / 320 / 310.
Positioning Notes: On a clear beat with constructive guidance, consider watching for pullbacks as potential entry points. If results are merely in line or guidance is cautious, be mindful of short-term volatility and avoid chasing strength. Position sizing and stops should be adjusted according to individual risk tolerance.
Disclaimer: The above content is for informational purposes only and does not constitute investment advice.





