Institutions: The resilience of gold prices reflects the risk of the game between the Federal Reserve and the White House; the underlying logic for long-term bullishness remains intact
汇通网 September 16 News—— US long-term Treasury yields have climbed to a near 20-year high, and markets widely expect the US Federal Reserve to hike rates this week. Gold continues to face selling pressure, but Thu Lan Nguyen, Head of Commodity Research at Commerzbank, points out that gold prices are showing stronger-than-expected resilience. The core reason is that markets are hedging against an imminent policy conflict between the Federal Reserve and the Trump administration. The bank has lowered its year-end gold price target, but its long-term bullish outlook remains unchanged. The fading US dollar safe-haven premium and rising risks to global sovereign debt continue to support gold's asset allocation value.
Driven by ongoing inflationary pressures, markets expect the Federal Reserve to raise rates, sending US Treasury yields higher to a near 20-year peak, which has led to continued selling in the gold market. However, Commerzbank offers a different view. While gold prices face selling pressure, the support underneath remains solid, and the resilience of gold prices is worth noting.
Thu Lan Nguyen, Head of Commodity Research at Commerzbank, analyzed in the latest research report that the market currently prices the probability of a Fed rate hike this week at about 90%. Additionally, rising tensions in the Middle East are pushing up oil prices, further lifting global interest rate expectations. It’s not only the US market that is affected.
Gold Resists Downside Move Amid Policy Battle Between Fed and the White House
Thu Lan Nguyen says,
Thu Lan Nguyen notes that facing persistently high inflation, the Federal Reserve is under constant pressure to hike rates, while President Trump has already issued strong warnings that if the Fed refuses to cut rates, he will take extreme measures. A direct conflict between the two sides is almost inevitable, and the financial markets are increasingly pricing in this risk. She adds,
She analyzes that this also explains why, despite US Treasury yields hitting near 20-year highs, the US dollar remains under pressure and dollar risk premiums continue to rise in the options market.
Short-term Target Cut for Gold, Long-term Bullish Logic Remains
Gold itself does not generate interest income, so rising rates increase the opportunity cost of holding gold, thus weighing on gold prices. However, this German institution judges that gold’s downside is limited before year-end. Commerzbank lowered its gold price forecast in July, cutting its year-end gold price forecast from $4,800 per ounce previously predicted in June to $4,500 per ounce.
Thu Lan Nguyen mentioned that the bank’s long-term bullish outlook for gold remains unchanged, and structural factors driving gold higher in the first half of this year are still present.
Conclusion
Overall, gold is currently in a special stage of tug-of-war between bulls and bears. High US Treasury yields and expectations of a Fed rate hike are bearish drivers weighing on gold. In contrast, challenges to the Fed’s independence from political forces, softening US dollar safe-haven status, and global sovereign debt risks form gold’s underlying support—these are also the key reasons gold prices have maintained resilience against selling pressure. In the short term, Commerzbank has lowered its gold price target, reminding investors not to chase gold at current levels, but the long-term structural positives remain intact. Future developments regarding Fed policy decisions, as well as the evolving policy conflict between the White House and the Fed, will continue to steer both gold and dollar market trends.
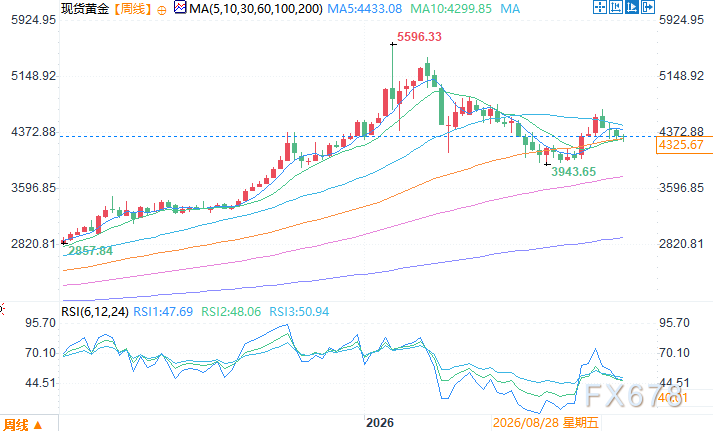
Spot gold weekly chart Source: FX678
GMT+8 September 16 12:01 Spot gold quoted at $4,327.67 per ounce





