News>
Why watch GME right now? rGME: Cohen buying, collectibles in authentication, stores restocking.
By:
1. Why GME now? What story is the market telling?
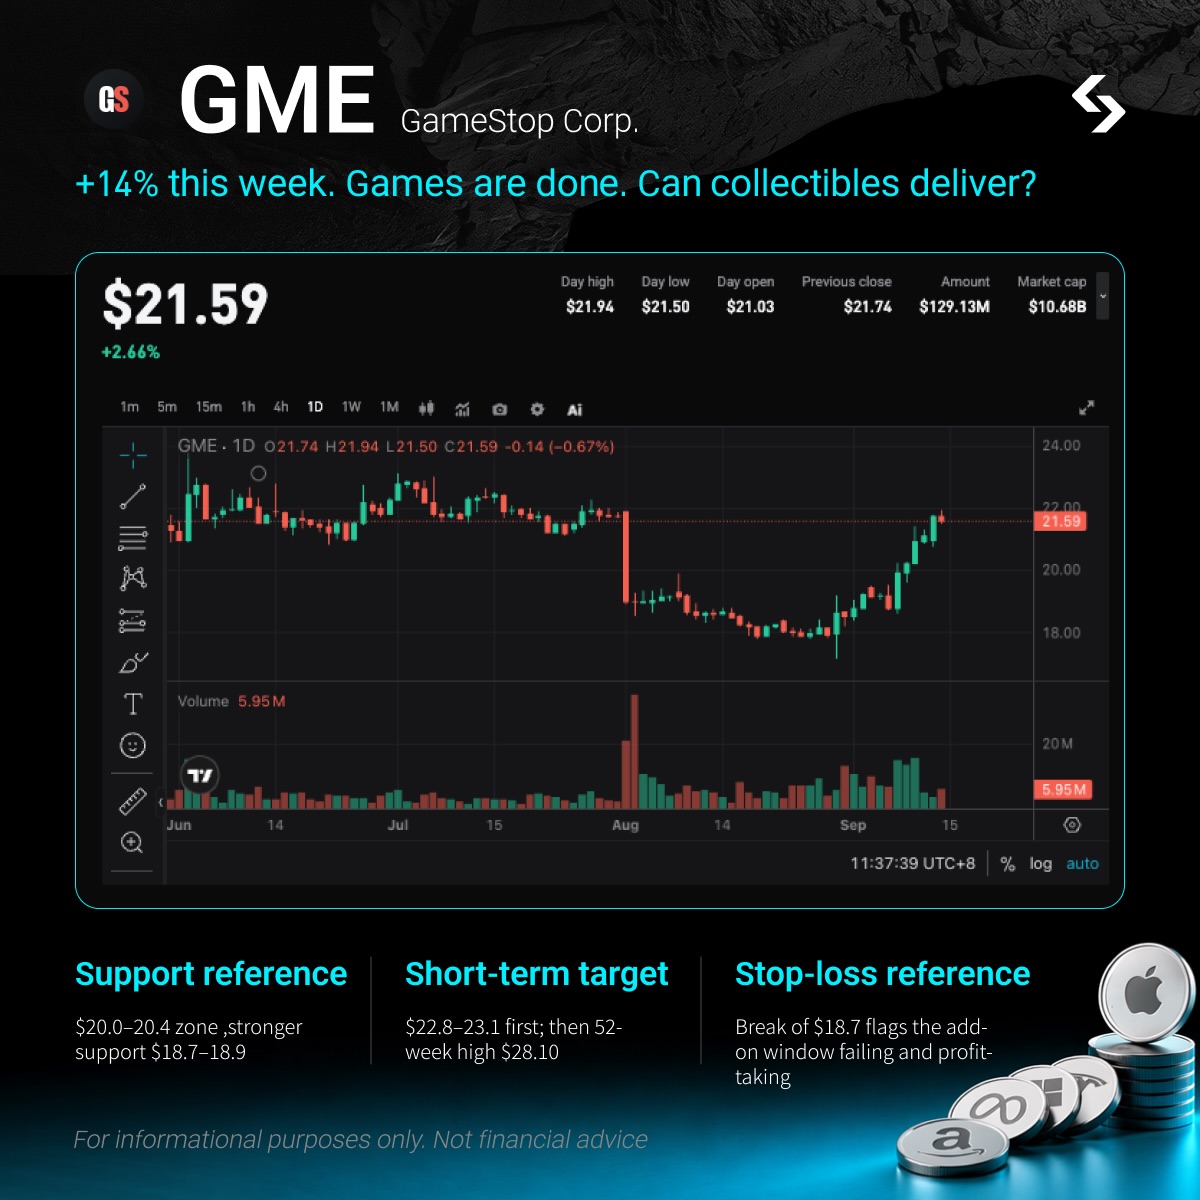
GME is not a new name. It is an old meme being repriced: a shrinking physical-game retailer recast as a capital-allocation platform with a thick cash pile, collectibles already more than half of sales, and a large eBay equity stake on the books. Spot is about $21.6 (Sep 14 close $21.62), market cap about $10.9B. Last 7 days about +14%, last month about +16%, 52-week range about $17.79–$28.10.
Roughly 23% below the high; getting back to that high still needs about 30%. RSI is near 70 — the short-term tape is not clean — but the stock is not sitting on the 52-week high. Short interest is about 12%–13% of float (~ 57M shares), average daily volume about 6.0–7.5M, days-to-cover about 7–10. Beta about 1.71. There is only one live question: earnings are already out and the CEO has added with real cash. The market is checking whether “collectibles growth + store-footprint stabilization” can turn one beat into a durable profit platform.
Q2 (quarter ended Aug 1) dropped Sep 8: revenue $790.2M vs $972.2M a year ago, but above the ~ $757M consensus. Adjusted EPS $0.27 vs ~ $0.19. Operating income $160.2M, the best Q2 operating profit in company history. Adjusted EBITDA $174.0M vs $75.7M. Full-year adjusted EBITDA guidance raised from “more than $600M” to “more than $650M.” The pricing reset is not consoles. It is collectibles: $356.3M, +57% YoY, 45.1% of sales. Video-game sales fell from $494.6M to $263.2M. On Sep 10 Ryan Cohen bought 1M shares in the open market at a weighted average of about $20.38, roughly $20.4M, lifting direct holdings to about 39.35M shares (~ 7.8%), or about 8.5% beneficial including warrants.
The same day the official account said “select closed stores” would reopen nationwide from Sep 11. The on-the-record count started at “at least one” (Brooklyn, Ohio). Do not write this as a national expansion wave. It is a signal that the closure cycle may be bottoming.
This is not “2021 squeeze, again.” It is three things stacked in one week: an earnings beat, the boss buying stock, and collectibles crossing half of sales. The short book is still there, but the size and days-to-cover are nowhere near the old squeeze. The elasticity comes from the event window and community heat, not from a two-day squeeze.
2. Business snapshot
What is vertically integrated here is not compute. It is store touchpoints + a collectibles assortment + the balance sheet. Grapevine, Texas does not matter. The market cares that Cohen finished the cost cut, put growth on trading cards, collectibles, and apparel, and is using cash and equity for a second engine.
The eBay stake is about 43.4M shares, ~ 9.8%, fair value about $4.9B as of Aug 1 — the largest non-operating variable on the books, and the piece most easily written up as a “takeover option.” Cash, cash equivalents, marketable securities, and digital assets total about $5.4B. In early September GameStop retired about $1.4B of converts with ~ 55.5M new shares plus $358.4M cash; long-term debt fell to roughly $2.8B. The share count went up; the interest burden went down. Closing stores and cutting opex is easy to copy. A collectibles supply chain and Cohen’s capital-allocation credibility are not.
Core products and operations Collectibles: trading cards, toys, apparel, pop-culture merch. Already the largest category in Q2. Mix lifted gross margin to about 43.7%. Floor space and fixtures keep moving this way. Hardware / software / pre-owned: still on the P&L, but management has said software is no longer the center of the company. Q2 game sales almost halved on a Switch 2 anniversary comp, store closures, and the France sale. Store network: U.S. stores from 2,900+ in early 2024 to under ~1,600. Select closed locations started reopening Sep 11. Count undisclosed. Treat it as footprint stabilization, not a new opening cycle. eBay stake: ~ 9.8% / ~ $4.9B.
In May, a non-binding $125/share bid valuing eBay at ~$56B; the board rejected it. The more realistic path is partnership (in-store authentication, fulfillment, collectibles assortment), not a near-term takeout. Q2 GAAP net income of $298.7M includes ~ $166.3M gain on an eBay-related derivative and ~ $72.1M unrealized gain on the equity stake, partly offset by ~ $75M of digital-asset losses — separate operating profit from investment marks. Capital structure: TTM revenue ~ $3.55B, TTM net income ~ $893M, EPS ~ $1.52–$1.53, P/E ~ 14. Cash-heavy, EV ~ $10.2B. It prices like a retail shell plus an investment company.
3. Key financials already disclosed
Q2 revenue $790.2M (prior $972.2M, -18.7%; consensus ~ $757M); operating income $160.2M (prior $66.4M); adjusted EBITDA $174.0M (prior $75.7M); adjusted EPS $0.27; GAAP net income $298.7M, diluted EPS $0.51. Collectibles $356.3M, +57%, 45.1% of sales (prior-year 23.4%); video games $263.2M;
pre-owned/refurbished $170.7M. SG&A $187.1M, still coming down. First-half adjusted EBITDA $339.7M; free cash flow about $393.6M. Full-year adjusted EBITDA outlook raised to more than $650M. Cash + securities + digital assets ~ $5.4B; eBay stake ~ $4.9B; total debt ~ $4.3B (long-term debt ~ $2.8B after the exchange).
Shares outstanding ~ 504.5M, up ~ 25% YoY — dilution is the price of the exchange. Cohen bought 1M shares / ~ $20.4M on Sep 10. Directors Cheng, Grube, and Attal bought smaller blocks around the same window. One of the largest open-market insider buys this year; the last similar-sized Cohen add was in January.
4. Expectations gap
Street consensus: sales are still falling, profits lean on eBay marks and one-offs, store reopenings are PR, and Cohen’s buy did not move Wall Street (Barron’s literally: the Street barely blinked). Analyst coverage is thin; there is no real consensus target. The stock has already been marked with a “shrinking retail + dilution” discount.
What may be different: record Q2 operating profit came from mix and cost, not only investment gains. Once collectibles are more than half of sales, the model is cleaner than “wait for the next console.” The gap to close is not “meme squeeze incoming.” It is whether collectibles mix and EBITDA guidance can print for another quarter. Dilution already hit in early September, so the “surprise ATM smash” weight is lower.
The real falsification is collectibles growth rolling over, reopenings going nowhere, or eBay stock taking another 10% out of the $4.9B mark. A 12% short book is not 2021 dynamite, but Superstonk / WSB heat picked up after the print and the Form 4. In an event window, that amplifies both sides. It will not be a linear repair.
5.Catalysts
Already done: Q2 beat + EBITDA guide to >$650M; Cohen’s Sep 10 1M-share buy; select store reopenings from Sep 11; ~$1.4B convert exchange closed; eBay stake locked in at ~9.8%. Live window (mid-to-late September): FOMC Sep 16 — the week’s biggest macro print. GME’s beta is ~1.7; risk appetite will reprice before the story does. Watch for a real reopen list and store count; collectibles holiday intake and card prices; any hard eBay authentication/partnership proof. Next earnings around early December (Q3, quarter-end Oct 31). That is the second report card on whether 45% collectibles mix is a platform or a one-quarter pulse. AMC still trades as meme-beta.
6. Levels (reference, not a call)
The tape is clean enough for an event swing: real insider cash + post-earnings repair + community heat. The stock has already lifted from the $18.7–$19 area to $21.6. Trade it as “post-print repair + CEO confirmation,” not as “just doubled off the lows, next stop $28.” Support: $20.0–$20.4 (Cohen’s $20.02–$20.47 buy zone; Sep 10 close $20.39). Stronger support $18.7–$18.9 (Sep 8 earnings-day low $18.72 / close $18.89). Below that, $17.79 (Aug 20 52-week low). Near-term upside: hold and the tape can look at $22.8–$23.1 (recent 3-month highs). Above that is the $26.9–$28.1 52-week high band — that needs another collectibles print or a harder catalyst than “select reopenings.” Stop reference: a clean break of $18.7 is sentiment giving back the add-on window. Do not underwrite an eBay takeover story through that. From FOMC night into the next U.S. cash open, allow a wider drawdown. Size first, levels second.
6. Risks
The biggest risk is mixing operating profit with investment marks. Strip out eBay marks and derivative gains and GME is still a retailer with falling sales. If collectibles growth rolls over from +57%, last week’s +14% can come off in one session. Second is dilution that already happened: ~ 55.5M shares for the exchange, float at 504.5M; ATM capacity and warrants remain supply. Further out: an eBay drawdown marks the $4.9B stake lower; if the takeover story is fully shut, the multiple goes back to “retail + cash”; if reopenings stay stuck at “at least one,” the Street will call it PR. Short interest at 12% and 7–10 days to cover can amplify both directions. It is not a 2021 squeeze structure. Beta ~1.7, and FOMC is this week. Position and stops matter more than the story.
Stock Limited-time Offer:August new user gift: Buy U.S. stocks and get free NVIDIA stock.Trade Now for Better Deals
New to stock spot trading? These videos will get you up to speed:
"Understanding Bitget Spot Stock Trading"
"Spot Stock vs. Stock Perps vs. Traditional U.S. Stocks: Pros, Cons, Ownership & Leverage"
"How to Pick the Right Stock Tokens & ETFs on UEX? 2 Key Metrics to Help You Avoid Costly Mistakes"
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
Trade now!
You may also like
Crypto prices
More





Become a trader now?A welcome pack worth 6200 USDT for new users!
Sign up now